What a time it’s been for Workday. In the past six months alone, the company’s stock price has increased by a massive 40.1%, reaching $192.03 per share. This was partly due to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Workday, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Workday Not Exciting?
We’re glad investors have benefited from the price increase, but we’re cautious about Workday. Here are three reasons you should be careful with WDAY, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
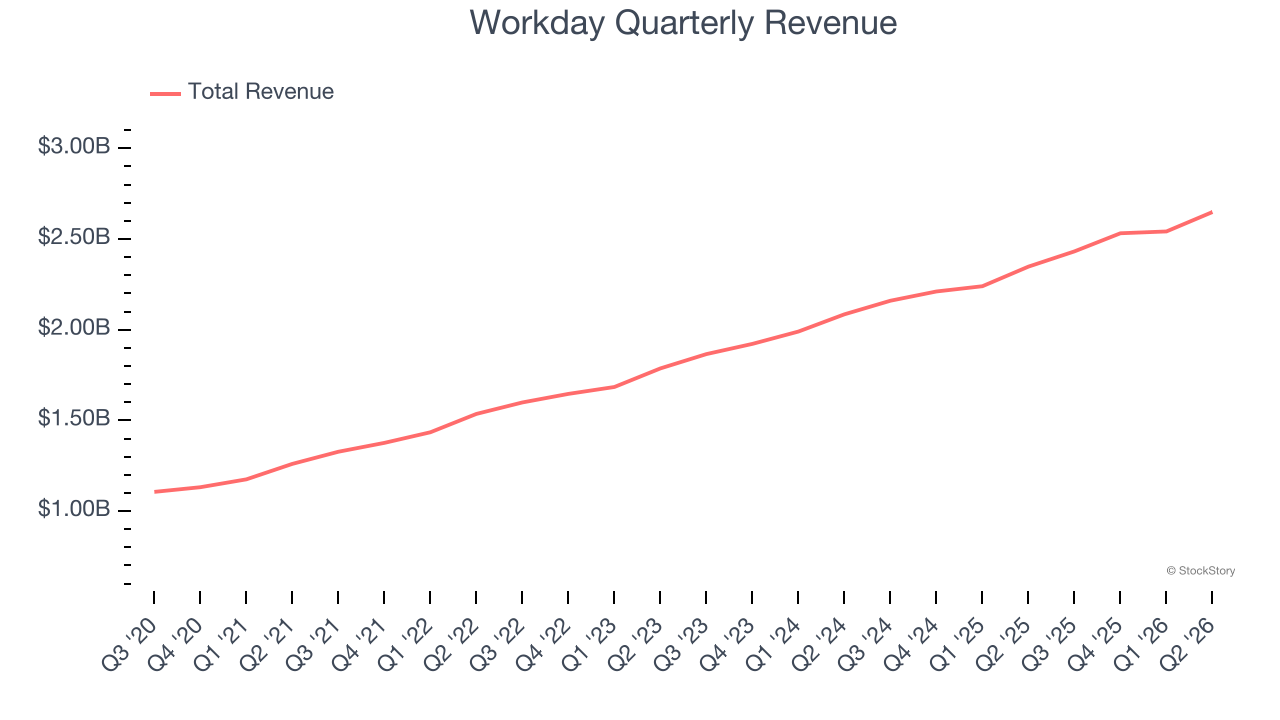
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Workday grew its sales at a 16.8% compounded annual growth rate. Although this growth is acceptable on an absolute basis, it fell slightly short of our standards for the software sector, which enjoys a number of secular tailwinds.
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Workday’s revenue to rise by 10.1%, a deceleration versus its 16.8% annualized growth for the past five years. This projection is underwhelming and indicates its products and services will face some demand challenges.
3. Operating Margin Rising, Profits Up
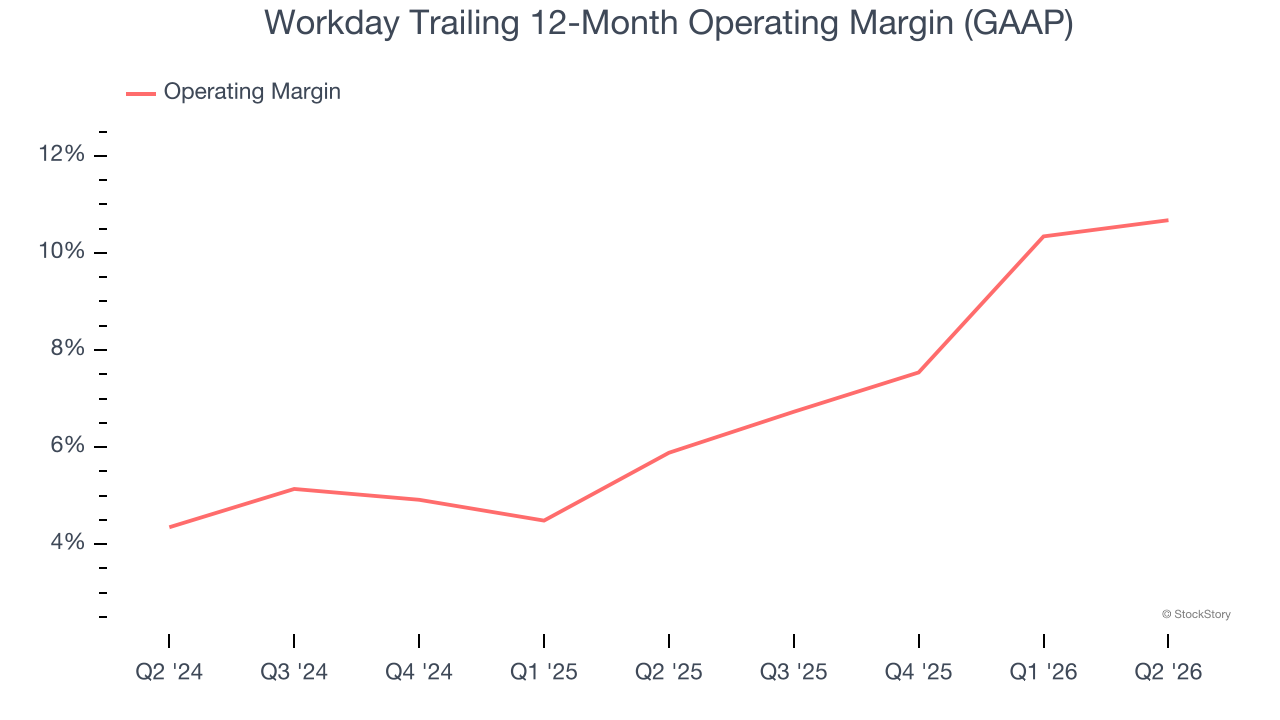
While many software businesses point investors to their adjusted profits, which exclude stock-based compensation (SBC), we prefer GAAP operating margin because SBC is a legitimate expense used to attract and retain talent. This is one of the best measures of profitability because it shows how much money a company takes home after developing, marketing, and selling its products.
Looking at the trend in its profitability, Workday’s operating margin rose by 4.8 percentage points over the last two years, as its sales growth gave it operating leverage. Its operating margin for the trailing 12 months was 10.7%.
Final Judgment
Workday isn’t a terrible business, but it isn’t one of our picks. Following the recent rally, the stock trades at 4.3× forward price-to-sales (or $192.03 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better investments elsewhere. We’d recommend looking at our favorite semiconductor picks and shovels play.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.